Alex Segre/iStock Editorial via Getty Images
Opener
I like to invest in the highest quality businesses in the world, and 90% of my portfolio is built with such businesses. However, I do like to make value bets from time to time, giving valuation an edge over quality. Now, I wouldn’t say Dr. Martens (OTCPK:DOCMF) is a bad company, especially since it is a long-lasting business capable of generating good ROIC/ROCE. Yet, the fact that it is a business with only one brand in the competitive fashion industry makes it less favorable as a long-term investment. So, if the price weren’t as attractive today, I wouldn’t even take a look at it. But I believe the market is missing this one. Basically, the current price assumes almost no growth for the stock. I think this is far from the truth, especially with the high brand value of the boots. Let’s dive in.
Business & Industry
Dr. Martens is one of the biggest boot brands in the world, boasting a rich history since the 1960s. It is built upon the rebellious status of being different, perhaps gothic or punky. I’m sure you know the classic pairs; those are timeless. In fact, the classic boots account for almost half of the business. I appreciate how the management treats this half as a premium brand to preserve brand equity. Here is what the CEO said about it:
We also manage the brand using the mentality of a luxury brand – for instance price discipline, never discounting our continuity iconic products, managing supply to wholesale and continually investing in the brand and our relationship with consumers. This approach I believe will further reinforce the sustainability and longevity of our future growth.
Today, Dr. Martens currently sells to over 60 countries, with over 80% of sales deriving from the UK, US, Japan, Germany, Italy, and France. The global supply chain consists of material suppliers, supplier factories, and distribution centers. Dr. Martens has 11 distribution centers globally, the majority of which are third-party operated. The products are made across 14 footwear assembly factories in Southeast Asia, together with the ‘Made In England’ factory in Northampton.
The marketing strategy is influenced by alternative consumers who have their own individual style with a proud sense of ‘self-expression’ at the core. The brand resonates with and is worn by, a much broader audience of wearers, such as those who value quality, durability, and heritage, and those who are focused on being stylish. Dr. Martens’ social media presence continues to deliver high engagement levels versus peers, demonstrating the depth of consumer connection with the brand.
DM’s brand (docs ir)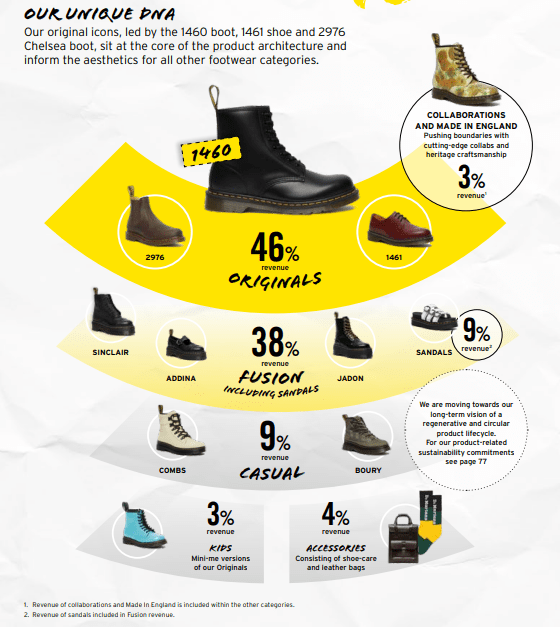
The brand is strong. According to Dr. Martens, it has a steady brand awareness of 72% and 48% familiarity. And let’s face it, how many brands, except for luxury brands, do you know that have lasted strongly since the 1960s? Given all that, let’s see what opportunities lie ahead.
The Opportunity
Dr. Martens’ target is to become a 2 billion revenue company. How do they plan to achieve it?
Firstly, their primary strategy is to focus on Direct-to-Consumer sales. This approach enables them to get closer to customers and improve margins. Currently, 61% of their revenue comes from DTC channels, including retail stores and e-commerce. Interestingly, physical retail is the strongest revenue segment so far this year, likely due to store openings, and it’s the only segment showing growth.
Secondly, they plan to increase marketing expenses to reach 7-8% of revenue. Although this may reduce margins slightly in the short term, it could stimulate top-line growth to compensate for this.
Thirdly, they aim for global expansion. While Dr. Martens is already a global brand, there’s still significant room for growth in some of the wealthiest markets. For instance, the UK currently has 32 pairs per capita (‘PPC’), indicating substantial potential for growth in other priority markets. These include the US (18 PPC), Germany (15 PPC), Italy (8 PPC), France (7 PPC), Japan (4 PPC), and China (less than 1 PPC). Dr. Martens believes that the long-term improvement in PPC in these markets will propel them towards becoming a £2 billion global footwear brand.
Fourthly, the boots market is projected to grow, potentially faster than GDP. Despite the current price of Dr. Martens suggesting a significant loss of market share, considering the aforementioned reasons and the growth over the last decade, this outcome seems unlikely.
In the past year, and likely in the upcoming one, Dr. Martens has experienced a slowdown in the overall market and a decline in their wholesale segment, impacting top-line growth. However, the growth in DTC channels is promising, especially given the management’s focus in that area. Wholesale was affected by both planned strategic decisions to reduce volume sold to EMEA retailers and terminate distributor contracts in China, as well as weaker wholesale performance in the Americas.
Numbers & Q3
The history of Dr. Martens, or Docs, is pretty impressive. Prior to the 2023-2024 slowdown, the revenue growth was linear and profitable. This gives me hope for further growth in the future and to believe the management’s claims about wholesale issues and the general market slowdown.
Looking forward, Docs can achieve growth through store count expansion; it currently has 235 stores, with a target of around 35 stores a year. That’s over 10% store count growth, which means that just from store expansion, we could see top-line growth that the market does not appreciate. Add to that the e-commerce site, which it stated is the most valuable asset. Maybe we won’t see those high teens growth rates, but based on recent history and the fact that 50% of the boots are timeless, I’m sure that looking forward, over the current downturn, we could see further solid long-term growth.
DOCS growth (finchat)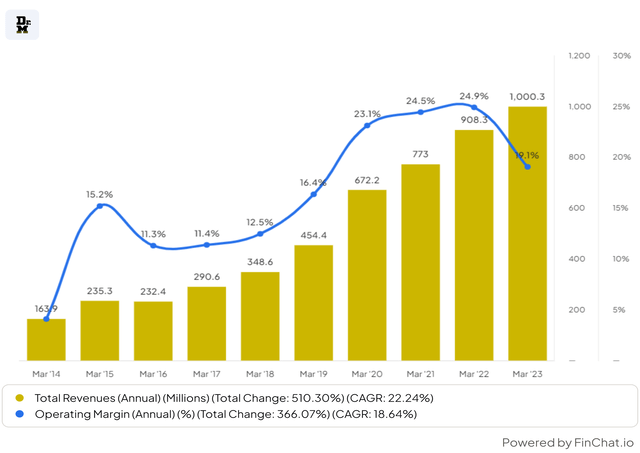
Docs presently has operating leverage, which means that when revenue is dropping, so are margins at a faster rate, but when it is increasing, the margins jump higher as well. This is because of the nature of fixed costs.
We saw the EBIT margin reach the mid-20s in ’22; since it dropped, but given the business structure, and since the second strategic target of Docs is to improve margins, I can see margin expansion, maybe to the previous margins we witnessed.
This margin growth could enhance another factor I like about Docs, which is the ROC numbers. Growth in NOPAT could lead to higher ROIC. A study by the great Michael Mauboussin showed that high ROIC companies tend to outperform, especially if this number is growing (you have to have top-line growth as well).
ROC (finchat)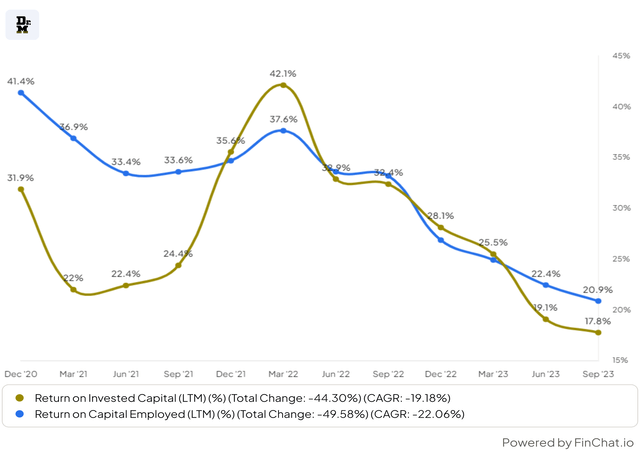
I wouldn’t say I’m a fan of Docs’ balance sheet, especially given that their debt is maturing as early as February ’26, which means they will likely need to take on more debt to pay it, or sacrifice dividends, which surely would be bad for the stock. But I don’t see it as a major risk. Two years of strong FCF would cover almost all of the more than 300M pounds debt.
I’m a buyback dude; I don’t like dividends because of the taxes. I think that instead of paying around a 50% payout ratio, and 80% in the first half of ’24, it would be more wise to buy back loads of shares at those prices, boost the EPS and FCF per share, and stabilize the stock price. Management probably thought about that and initiated a 50M buyback program. Now I think it’s a great time to deploy it. In the first half of FY ’24, Docs bought 20M shares at a much higher price than now.
As for Q3, total revenue was down 10 CC, mainly due to a huge drop in wholesale sales. Retail revenue was the only segment up. The disturbing part is the e-commerce, which was also weak with an 8 CC decline.
Wholesale revenue declined by 49% reported, or 46% CC; significant decline was seen in both Americas and EMEA, in line with both our expectations and the assumptions within our FY24 guidance. Wholesale customers continue to have relatively low levels of in-market inventory, however the timing and level of re-orders is unpredictable, meaning that our visibility over wholesale remains weak.
The guidance is for a high single-digit decline in FY 2024.
Ownership
Insiders bought shares back in June and July when the price was much higher than it is now, indicating that the managers believe in the future. Among them is the CEO, Kenny Wilson, who bought almost 400k GBP. Insider ownership is mainly high via Tara Alhadeff, who represents Permira, the PE firm that IPO’d Docs. I like that managers seem aligned with shareholders; they also suffered serious sums of money evaporated and will likely strive to earn it back.
Valuation
DOCMF is a company I looked into because of the price, and it is appealing. Trading at 8 times LTM earnings, this appears to be a good price for a company that can generate high FCF and ROIC. Also, assuming Docs will manage to grow a fraction of its past growth, we could see a PEG ratio under 1, if we assume mid-single-digit long-term growth along with margin expansion. Based on past growth and brand strength, this seems achievable.
Looking into DCF makes DOCMF stock look interesting. Inputting analysts’ consensus FCF for the first 3 years and thereafter assuming 5% growth, 3% terminal growth, and a WACC of 7.5% (it was misleading to determine WACC because, since the IPO, the stock just crashed, resulting in a negative beta. I input 1 in the beta to see a more balanced WACC calculation). The result is that the stock is extremely undervalued, maybe by 100%. Basically, the current price suggests that no growth at all will be achieved from the 100M FCF level, which seems to me a bit unlikely.
DCF (omnicalculator) DCF (omnicalculator)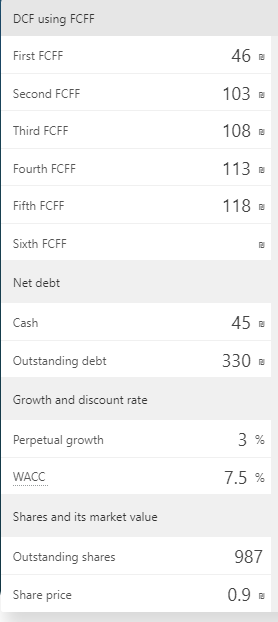
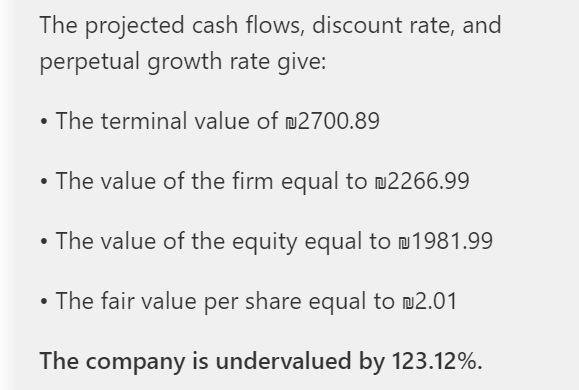
Risks & Conclusions
The risks lie in Docs’ inability to regain its margins and resume its growth path. However, given its brand power, I see this as unlikely. Another risk is the debt load on the balance sheet, which might hinder dividend payouts and could lead to a sell-off from yield seekers. Docs is a premium brand; however, as we saw in the recent American sales during a recession, consumers may not readily purchase $200 boots. It is not a luxury brand immune to market downturns.
Additionally, there is a risk associated with the low volume in the OTC market, which could lead to liquidity problems. Therefore, I would prefer to buy on the LSE.
Considering the strong, long-lasting brand and the high returns on capital, I believe the low price compensates for the risks. Therefore, I rate the stock as a STRONG BUY.
Looking forward to your comments.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link