
janiecbros/E+ via Getty Images
The gaming peripheral and component space has had a rough past few years. After an incredible Covid-19 induced boom in 2020 and 2021, the recent past has been difficult for the computer and peripheral space. However, after a period of weakness from Corsair Gaming (NASDAQ:CRSR), the stock fundamentals are now poised to improve into 2024 and 2025. After a period of cyclical digestion with many who needed components having already bought them, the market has bottomed out and is able to grow again. Long term, the gaming market is lucrative, with growth among enthusiasts driving Corsair with their premium priced offerings. This should allow margin expansion over time, which is the biggest factor in Corsair becoming solidly profitable through all cycles. Corsair has a strong brand in the market, especially in areas such as RAM and keyboards. They also have a growing presence in the streaming area with its Elgato products. Since the market is quite fragmented, CRSR is in a great position to acquire additional brands over time and strengthen its position as a leader further. However, the company continues to dilute shareholders, and having a small operating income margin is hurting potential share gains. The valuation makes it a buy, but the stock will prove to be economically sensitive, with a high variation in earnings over time.
Q4 – Financial Improvement But High Dilution
2022 was a difficult year for CRSR as component sales plummeted from pandemic-era peaks. However, in Q4 2023 components rebounded nicely for solid growth. Revenue for Q4 2023 was up 16% over 2022 to $417.3 million, driven by a large improvement in the peripheral category at Christmas. Components performed better throughout the year, however, with peripherals being more weighted to holidays. Inventory levels have finally normalized though in the supply chain, with Corsair calling out low inventory in some of the popular new products added through 2023. This is a solid data point of potential revenue upside in 2024 if the consumer holds strong. On the downside, operating margins continue to stay low at just $23.2 of adjusted net income or 5.5% operating margin. High fixed costs continue to make it difficult to ramp operating margins as fast as Corsair would like.
They have continued to add to their ICUE Link system by streamlining the PC building process with new RX series fans. This reduces complexity for new builders plus improves cable management for everyone, improving the customer experience. Adding continued capabilities and acquisitions of other brands are the best way for CRSR to add growth here. This category has superior margins, so longer term it will likely provide more net income for Corsair. While the debt load is reasonable for Corsair, it will be difficult for the company to improve margins enough to overcome interest costs in the medium term. Also, CRSR stock-based compensation increased in 2023 and dilution of almost 6% over the past 2 years due to the November 2022 offering is significant. Management should slow the pace of dilution in 2024 with $178 million in cash on hand. The company has sufficient capital now for smaller acquisitions and shouldn’t need to raise money again in the medium term.
Gross Margins Corsair (CRSR IR)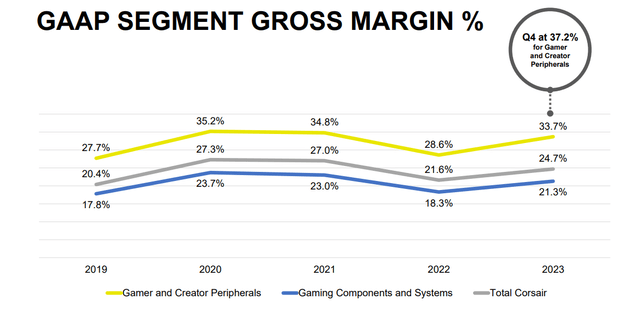
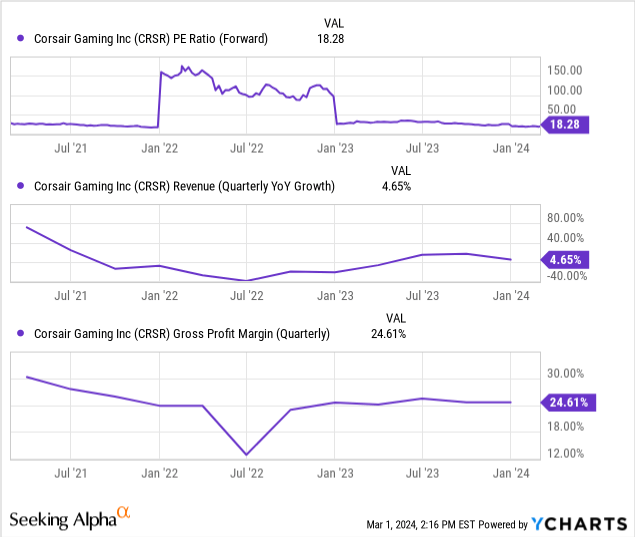
In my view, gross margins are back to a solid baseline of 24% company-wide. In Q4, the gamer peripheral area margins were an impressive 37.2%. This shows that as they continue to scale the Elgato brand, they will be able to improve margins above past peaks around 35%. Revenue in this cohort of products grew 16.1% y/y to $136.8m. This should bode well for a strong start to 2024 in this area as new launches continue to impress. The gaming components section is more dependent on the wider fragmented component pricing situation. That said, margins in this area should rebound in 2025 if the economic situation improves. The days of 30% margins are likely a Covid-19 boom phenomena and unlikely to return in the near future. This would require a reset in interest rates and a large increase in money for the younger cohort that makes up most gamers. As you can see below, the current forward P/E estimate is 18x 2024 earnings, quite expensive for a stock with low margins and difficulties remaining profitable.
Growth is lumpy for CRSR, with a significant drawdown in revenue growth since the 2021 peak. 2024 is expected to see 5% revenue growth, which is fair considering the valuation of 18x Forward earnings. While CRSR is still facing headwinds relating to lower PC component demand, valuation is now at a level that is supportive of the shares going forward. Personalization of products is a strong trend among many consumer goods companies, and CRSR plans to lean into it in the coming years. These products sell at a 10% premium for little extra cost to CRSR, improving margins and delighting customers. Margins overall will improve from here with scale and improved execution by management on cost initiatives.
Conclusion – Speculative Buy
While CRSR is a strong leader in their space, they have yet to parlay it into significant earnings power. However, as others in their space show, they have the potential to increase margins in earnings as they scale in the coming years. This may take some time as the company will need to scale products as well as acquire more brands to take advantage of their leadership. They have strong brand power among the gaming and online creator community, giving them a long-term advantage in marketing. CRSR is a stock to hold for a long 5-year or more horizon, as it will take some time to fully realize the potential of their ecosystem and ramp margins to the level of peers of 30%+. This should mean strong earnings growth in future years to come, but the stock will be volatile until its scale improves.
Credit: Source link