
kynny
Veeco Instruments (NASDAQ:VECO), a supplier of semiconductor process equipment, closed the books on FY2023 with the release of the latest Form 10-K. In general, FY2023 was a good year for VECO, which found its way back to the stock with strong gains. In fact, VECO was able to grow the top and the bottom line at a time when most suppliers of equipment used to manufacture semiconductors saw business contract due to a downturn in the equipment market. True, VECO is not a pure semiconductor play, but it was the semiconductor segment powering the outperformance, offsetting weakness elsewhere. However, there is more to the outperformance, which puts it in a different light. Why will be covered next.
VECO is in the midst of a rally
A previous rally rated VECO a hold after noting some contradictory aspects to VECO. On the one hand, the stock had powered ahead, driven by resilient earnings in a tough market. On the other hand, the article also noted surprisingly elevated short interest in VECO, far more than one would expect for a company with no obvious flaws.
This raises the question why shorts have decided to bet against VECO. According to the most recent data from the Nasdaq, short interest stood at 6,274K shares as of February 15, which is up for the year and which translates to a short float of 11.5%. It is not possible to know what is motivating each and every short out there, but the fact that there are so many out there is reason enough to take a closer look at VECO before going all in.
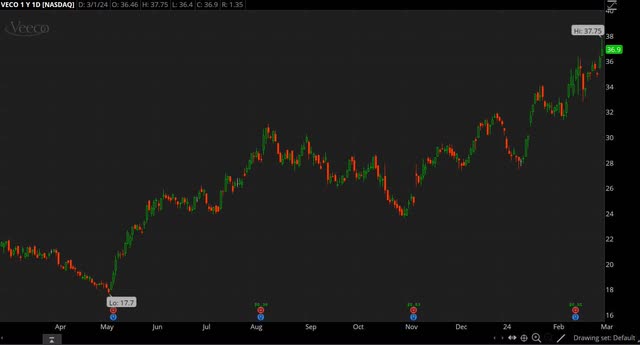
Source: Thinkorswim app
As far as the stock itself is concerned, there is certainly reason to be long VECO. The chart above shows how the stock has soared higher after bottoming in May 2023. The stock was worth $17.70 in May 2023, but VECO is now worth more than twice as much with the stock closing at $36.90 on March 1, 2024. If the trend or momentum is what matters most, then long VECO has strong arguments in its favor.
How VECO has outperformed
VECO has other arrows in its quiver. VECO has outperformed by managing to eke out growth at a time when others have not, which is another argument in favor of long VECO. Sources vary, but according to a recent report from SEMI, global sales of semiconductor manufacturing equipment shrank by 6.1% YoY to $100B in 2023.
In contrast, VECO grew FY2023 revenue by 3.1% YoY to $666.4M and non-GAAP EPS grew by 7.6% YoY to $1.69. In terms of GAAP, VECO ended with a net loss of $30.4M or $0.56 a share, but this was the result of refinancing of debt. In addition, GAAP income of $166.9M in FY2022 was aided by an income tax benefit of $117M, which pushed GAAP income to $128.9M or $2.00 per share in Q4 FY2022, skewing the YoY comparisons.
Semiconductor revenue contributed $413M or 62% of total revenue, up 12% YoY. Scientific revenue contributed $78M for a 12% share, up 15% YoY. These two helped offset contraction in compound revenue and data storage revenue, both with a share of 13% each. VECO ended FY2023 with cash, cash equivalents, restricted cash and short-term investments of $305.8M, partially offset by $274.9M of long-term debt on the balance sheet. The table below shows the numbers for FY2023 versus FY2022.
|
(Unit: $1000, except for EPS) |
|||
|
(GAAP) |
FY2023 |
FY2022 |
YoY |
|
Net sales |
666,435 |
646,137 |
3.14% |
|
Gross margin |
42.8% |
40.7% |
210bps |
|
Operating income |
69,940 |
60,296 |
15.99% |
|
Net income |
(30,368) |
166,942 |
– |
|
EPS |
(0.56) |
2.71 |
– |
|
Weighted-average shares outstanding |
53,769K |
65,607K |
(18.04%) |
|
(Non-GAAP) |
|||
|
Net sales |
666,435 |
646,137 |
3.14% |
|
Gross margin |
43.5% |
41.9% |
160bps |
|
Operating income |
109,574 |
99,820 |
9.77% |
|
Net income |
98,339 |
89,575 |
9.78% |
|
EPS |
1.69 |
1.57 |
7.64% |
|
Weighted-average shares outstanding |
60,843K |
63,436K |
(4.09%) |
Source: VECO Form 10-K
Guidance calls for Q1 FY2024 revenue of $160-180M, an increase of 10.8% YoY at the midpoint. The forecast sees GAAP EPS of $0.22-0.33, an increase of 61.8% YoY at the midpoint, and non-GAAP EPS of $0.36-0.46, an increase of 36.7% YoY at the midpoint.
|
Q1 FY2024 (guidance) |
Q1 FY2023 |
YoY (midpoint) |
|
|
Revenue |
$160-180M |
$153.5M |
10.75% |
|
GAAP EPS |
$0.22-0.33 |
$0.17 |
61.76% |
|
Non-GAAP EPS |
$0.36-0.46 |
$0.30 |
36.67% |
Source: VECO Form 8-K
In comparison, the table below shows the numbers in the preceding quarters. Note that the numbers would have been worse if not for strong contributions from the semiconductor segment. In Q4 FY2023, for instance, semiconductor revenue increased by 17% QoQ, negating softness elsewhere,
|
(Unit: $1000, except for EPS, margins and shares) |
|||||
|
(GAAP) |
Q4 FY2023 |
Q3 FY2023 |
Q4 FY2022 |
QoQ |
YoY |
|
Net sales |
173,924 |
177,366 |
153,799 |
(1.94%) |
13.09% |
|
Gross margin |
45.2% |
43.3% |
40.9% |
190bps |
430bps |
|
Operating income |
24,183 |
22,263 |
13,392 |
8.62% |
80.58% |
|
Net income (loss) |
21,637 |
24,574 |
128,915 |
(11.95%) |
(83.22%) |
|
EPS |
0.37 |
0.42 |
2.00 |
(11.91%) |
(81.50%) |
|
Weighted-average shares outstanding |
59,821K |
59,636K |
65,684K |
0.31% |
(8.93%) |
|
(Non-GAAP) |
|||||
|
Net sales |
173,924 |
177,366 |
153,799 |
(1.94%) |
13.09% |
|
Gross margin |
45.4% |
44.2% |
42.3% |
120bps |
310bps |
|
Operating income |
32,122 |
32,717 |
23,754 |
(1.82%) |
35.23% |
|
Net income |
29,823 |
31,040 |
21,891 |
(3.92%) |
36.23% |
|
EPS |
0.51 |
0.53 |
0.38 |
(3.77%) |
34.21% |
|
Weighted-average shares outstanding |
59,387K |
59,202K |
63,513K |
0.31% |
(6.50%) |
Source: VECO Form 8-K
What to expect from VECO in FY2024
VECO provided some insights into the outlook beyond Q1. VECO is calling for FY2024 revenue of $680-740M, an increase of 2.0-11.0% YoY, and non-GAAP EPS of $1.60-1.90, an increase of as much as 12.4% YoY at the high end. From the Q4 earnings call:
“And now for some additional color beyond Q1. Based on our current visibility, we’re reiterating our 2024 revenue outlook between $680 million and $740 million. We expect revenue in the second half of the year to exceed revenue in the first half based upon timing of scheduled shipments from our backlog, as well as forecasted orders. And we continue to forecast diluted non-GAAP EPS for the full year to be between $1.60 and $1.90 per share.”
Source: VECO earnings call
If VECO comes in at the midpoint, then this would imply a forward non-GAAP P/E ratio of 21.1x with EPS of $1.75 and a stock price of $36.90. This is above the average of 17.6x in the last 5 years for VECO, but it is below the sector median, which stands at 25x.
Is there something to be concerned about with regard to VECO?
On the surface, there is not much standing in the way of long VECO. Both the income statement and the balance sheet look fine. VECO is growing, and that’s with a sluggish market. If the market returns to growth as many expect it to, then VECO would be in an even better position. The charts are pointing in the direction of higher stock prices. Multiples are not unreasonable. In short, there is a lot in favor of long VECO.
|
(Unit: $1000) |
FY2023 |
FY2022 |
YoY |
|
USA |
162,790 |
197,433 |
(18%) |
|
EMEA |
76,697 |
87,837 |
(13%) |
|
China |
217,942 |
123,703 |
76% |
|
Rest of APAC |
208,693 |
235,735 |
(11%) |
|
Rest of the world |
313 |
1,429 |
(78%) |
|
666,435 |
646,137 |
3% |
Source: Form 10-K
However, there is one issue that should raise concern. Recent growth has been pretty much exclusively driven by China. While VECO was able to grow, most markets saw a drop in demand. If not for a huge increase in sales in China, VECO would not have grown. China contributed 19% or $123.7M to FY2022 revenue, but this jumped to 33% or $217.9M in FY2023 after revenue grew 76% YoY to negate weakness everywhere else. The table above shows how China was very much the outlier contributing to the recent results at VECO.
Should VECO be concerned the China tailwind could reverse for whatever reason?
China has been the tailwind making all the difference for VECO. However, it needs asking whether or for long how this tailwind can continue. The fact that China’s orders have increased by so much, as much as 76%, whereas everyone else is ordering much less, suggests that recent orders are not only driven by real demand, but also by inventory building.
Keep in mind that the U.S. government has imposed trade restrictions on China, some of which apply to VECO, especially as it relates to anything EUV or the leading edge. Most of what VECO supplies is allowed to be sold to China, but that could change in the future. Customers in China have thus an incentive to order more to hedge against possible supply chain disruptions with extra inventories. This could be the driving force behind the strong sales growth in China, which in tun has allowed for VECO to outperform in a less than ideal market.
VECO currently supplies equipment to China for mature process nodes and a high-ranking official at the Department of Commerce has recently stated that the U.S. government has no interest in expanding export controls to mature or legacy chips. Still, the U.S. Department of Commerce reserves the right to change its mind and, if it does, it won’t be the first time.
Recall how export controls have gotten progressively more strict. For instance, early on, the export controls were limited to process nodes of 10nm or smaller, but they have gotten progressively more strict with additional rules. For instance, there are now rules that apply to 16/14nm process nodes, which did not exist before. The precedent has been set and the U.S. government could decide to impose export controls on items that are currently sold to China, which could include most of what VECO sells to China.
The U.S. government has, for example, recently canceled the license it previously granted to Entegris (ENTG) for shipping certain materials to a customer in China, which gave ENTG permission to do business with the customer involved. The U.S. government can and does change its mind on occasion, so the possibility VECO may be denied the ability to trade with China at some point in the future should not be ruled out. This would not be good for VECO, considering how much growth was due to China in the first place.
Investor takeaways
There is a lot to be said in favor of long VECO. VECO’s ability to outperform by growing in a difficult market is impressive, especially when most have failed to do so. VECO is not expensive, trading at 21x forward earnings, which is less than what most in the sector go for. The charts suggest that long VECO is the way to go.
However, China being the driver of growth is worth paying attention to. It’s true VECO has outperformed, but the growth is misleading. If China had not ramped up orders, the top and the bottom line would have almost certainly shrunk in FY2023. China’s 76% YoY increase in sales is masking double-digit weakness everywhere else. The fact that China was the sole reason VECO grew at all in FY2023 puts the outperformance in a very different light and not in a good way. It raises doubts about the sustainability of this outperformance.
Granted, this exposure does not necessarily have to be a problem, especially in the short term. The U.S. government could let the trade continue, as it has stated recently, and VECO could continue to benefit accordingly, but if the U.S. government decides to change its mind once again, and impose trade restrictions where there are none at the moment, VECO could see its tailwind turn into a headwind.
It is very tempting to be long VECO with so much in its favor, but I am neutral on VECO in light of the above. VECO looks primed to build on its gains, but U.S. government policy is a wildcard that could disrupt everything. If the U.S. government does not intervene, recent trends can continue, but if it does, the shorts, which have increased their bets and thus taken a beating with the stock rallying, may have the last laugh after all.
Credit: Source link