
FotografieLink/iStock via Getty Images
Investment Thesis
PubMatic (NASDAQ:PUBM) holds approximately $170 million of cash and no debt, meaning that 10% of its market cap is made up of cash. Got you interested? How about if I told you that analysts’ revenue growth rate estimates are totally wrong? More interested now?
And now, what if I told you that PubMatic believes that its stock is undervalued and has sought to increase its share repurchase program, to return approximately 10% of its market cap in the coming two years?
Simply put, that’s the overall bull thesis.
Even though I’m not exuberant on the stock, as I believe that there are better adtech companies with more compelling risk-return profiles, the fact of the matter is that there’s more than enough to this stock to get me bullish on it.
Rapid Recap,
Back in December, in a neutral analysis, I made the case that the stock was cheap, but that I was on the fence as I questioned its prospects.
Author’s work on PUBM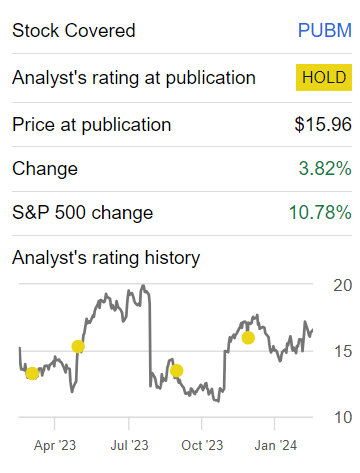
Indeed, I’d been on the fence for PUBM for a while now. But I’m now slightly bullish and believe there’s enough here to make me reconsider my original stance.
Why PubMatic? Why Now?
PubMatic provides a platform that helps online publishers (websites, apps, etc.) make money from displaying ads on their platforms. On one side, PubMatic works with publishers to efficiently monetize their ad inventory, ensuring that they get the best value for the spaces where ads appear. On the other side, they collaborate with advertisers and marketers, helping them reach their target audience by placing ads on various digital platforms.
PubMatic’s platform acts as a kind of middleman, connecting publishers who have ad space with advertisers looking to promote their products or services.
Moving on, PubMatic has pivoted its focus to nascent revenue streams, such as omnichannel video and display, and this strategy has proven successful, with these streams now constituting a low single-digit share of total revenue and expected to expand further in the upcoming year.
Next, PubMatic’s agility in adapting to industry changes, particularly post-cookie solutions, positions it well to navigate the evolving digital advertising landscape.
PubMatic’s strong position in Supply Path Optimization (“SPO”) is noted as a major growth driver, reaching over 45% of total activity. The company’s success in building SPO technology is paying off.
Despite its positive outlook, there are also challenges. A notable headwind is the impact of Yahoo’s changes, as they shuttered their SSP business in 2023. This move by Yahoo has created a sizable obstacle for PubMatic, reflected in a substantial year-over-year revenue decline when including Yahoo’s owned and operated inventory. Although, PubMatic has managed to mitigate this impact and guides to maintain consistent growth in 2024, which we discuss next.
2024 Organic Growth Rates of 12% CAGR
PUBM revenue growth rates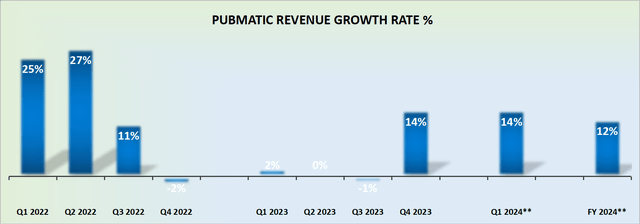
PubMatic beat Q4 revenue estimates by 8%. I know that everyone always expects to see their shares pop on the back of an earnings report, but this 8% beat is nothing short of remarkable!
SA Premium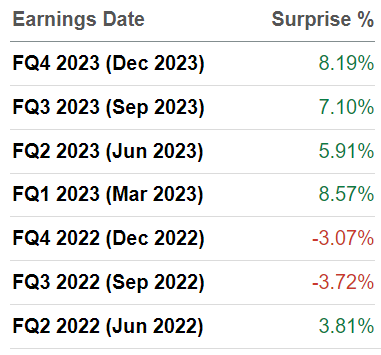
While PubMatic has frequently delivered high single digits beats, the fact that PubMatic’s guidance now points to 12% organic growth rates (excluding Yahoo! business) for 2024, demonstrates that this was not a one-off flash-in-the-pan quarterly beat. This is a company that has evidently turned around. And what’s even more alluring than its revenue growth rates is its valuation.
PUBM Stock Valuation — 13x EBITDA
For 2024, PUBM guides for approximately $90 million of EBITDA. This is a 20% increase from 2023 at approximately $75 million. Including the premarket jump, this leaves the stock priced at 13x forward EBITDA.
Is this a bargain? It’s certainly very interesting. Indeed, I wouldn’t be overly surprised to see PubMatic now re-rated closer to $1.5 billion in the near term. But that’s not a whole lot different from where the valuation is now, including the premarket jump. Alas, therein lies the problem with the bull case. The stock has just rocked too much too quickly.
The Bottom Line
In assessing PubMatic’s investment potential, the company’s solid financial position stands out, boasting approximately $170 million in cash and zero debt, constituting around 10% of its market cap. My optimism stems from PubMatic’s recent share repurchase program expansion, intending to return about 10% of its market cap over the next two years, indicative of perceived undervaluation.
Furthermore, PubMatic’s 12% organic growth rate guidance for 2024 and an impressive 8% Q4 revenue beat highlight a company that has demonstrably turned around!
The valuation, at 13x forward EBITDA for 2024, is intriguing, potentially prompting a re-rating closer to a $1.5 billion market cap in the near term. However, the extent of the recent premarket jump introduces an element of caution to my bullish thesis.
Credit: Source link