Karl Hendon/Moment via Getty Images
Investment Introduction
The last 52 weeks for Valaris Limited (NYSE:VAL) have been quite volatile with the trading range of $54.13 – $80 after shooting up fast in mid-2023 the stock has steadily been losing its valuation. VAL operates as an offshore contractor of drilling and when there started being cuts to OPEC production it meant that global oil prices quickly accelerated. For VAL, the effect was a skyrocketing stock price. The FWD earnings are multiple doesn’t quite tell the whole story with VAL right now, as it’s at 112x, an incredibly high multiple to pay for an energy company. VAL is in the works of rapidly improving its bottom line, and growth these next few years seems very appealing. The third quarter means additional contracts for the company, as well as the beginning of operations in Brazil. This will be visible on the next earnings report, coming on February 22. Buying into strong and positive management is important, and we have that here, so I will assess VAL as a buy.
Company Introduction
VAL is included in the energy sector, or more specifically in the oil and gas drilling industry. Here, VAL has carved out a space for itself as a company that focuses on offshore contract drilling services. The operations span globally, and keeping track of how VAL manages to expand into appealing markets is crucial. The company’s offshore drilling rig fleet is made up of various equipment, including advanced drillships, positioned and moored semisubmersible rigs, as well as versatile jack-up rigs. This lets VAL be quite flexible in their operations and lets them also engage in different markets around the world, just like they are now.
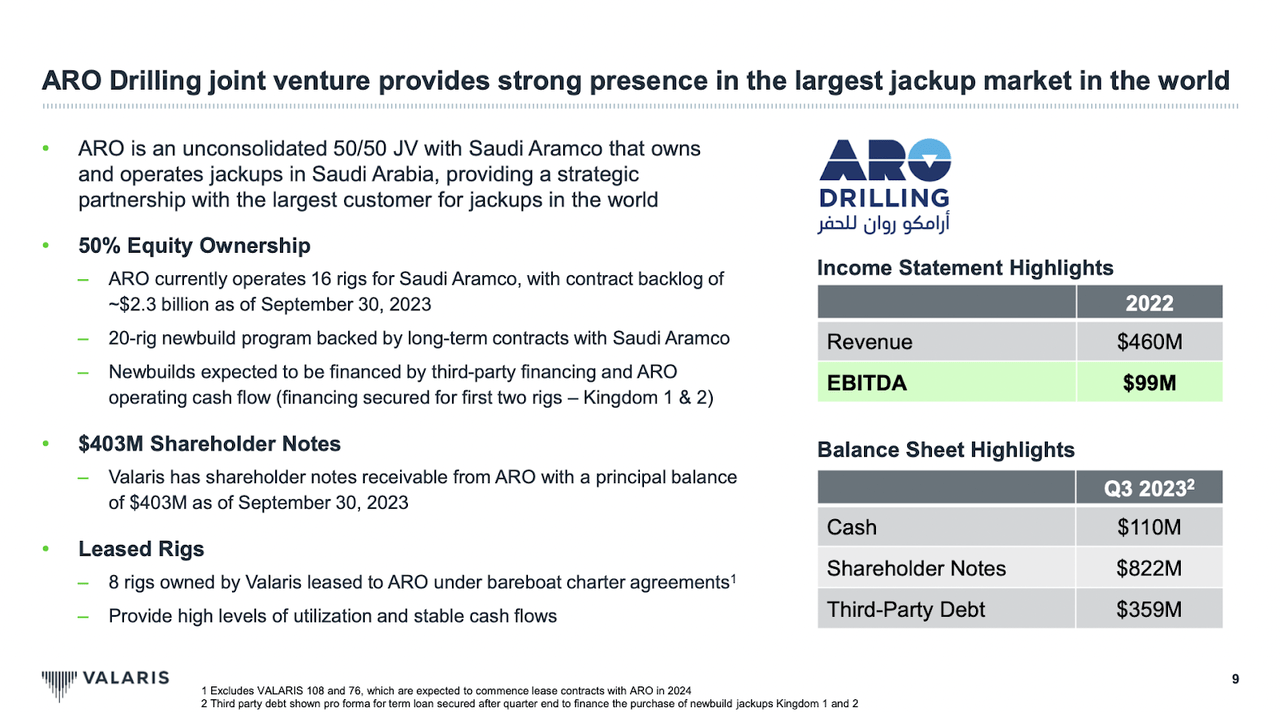
Joint Venture (Investor Material)
As a drilling contractor, VAL needs to place a lot of focus on establishing and securing partnerships and sometimes joint ventures as well. The joint venture between VAL and ARO Drilling, for example, gives VAL a foot in the door for the world’s largest jackup market. This 50/50 partnership with Saudi Aramco operates 16 rigs in Saudi Arabia, holding a substantial contract backlog. The collaboration also includes a 20-rig new build program supported by long-term contracts, with innovative financing strategies in place. VAL, benefiting from leased rigs to ARO, ensures high utilization and stable cash flows, contributing to their robust financial performance highlighted by substantial revenues and a solid balance sheet.
The state and growth of the business right now is solid, with CEO Anton Dibowitz adding the following in the previous earnings report:
“During the third quarter, we were awarded new contracts and extensions with associated contract backlog of approximately $465 million. Our long-term contract for VALARIS DS-7 was the seventh contract awarded to our previously stacked floaters since mid-2021. Following this reactivation we will have 10 drillships working and will remain disciplined in exercising our operational leverage with only one stacked drillship and two newbuild drillship options remaining”.
I think this comment highlights very well how the management of VAL is trying to expand its assets base in a fast fashion but also strategically. Even though a large portion of the operations as situated in the Middle East, I think that expanding into Brazil like VAL recently did is a showcase of them being well aware of how to position themselves not just for the next few years, but instead for the next several decades.
Valuation
Ratings Summary (Seeking Alpha)
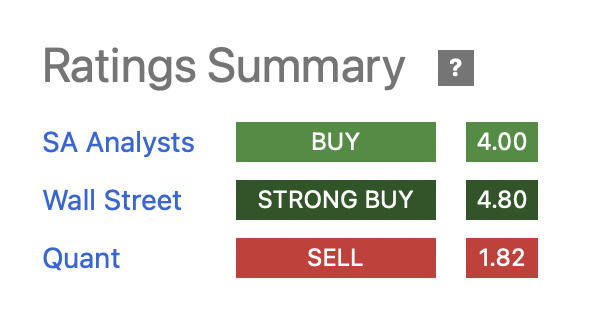
Ratings vary for the company, but the overwhelming positive as the only reason for the poor quant rating comes from the very high multiples VAL trades at. Now, the question arises as to why the business could trade so high and still deserve a buy rating from analysts. The management expected significant EPS improvements in 2024 and beyond as they deactivate drills at very favorable day rates. This is what investors are buying into and the reason for the EPS potentially jumping up to $9.33 by 2025.
Valuation Grades (Seeking Alpha)
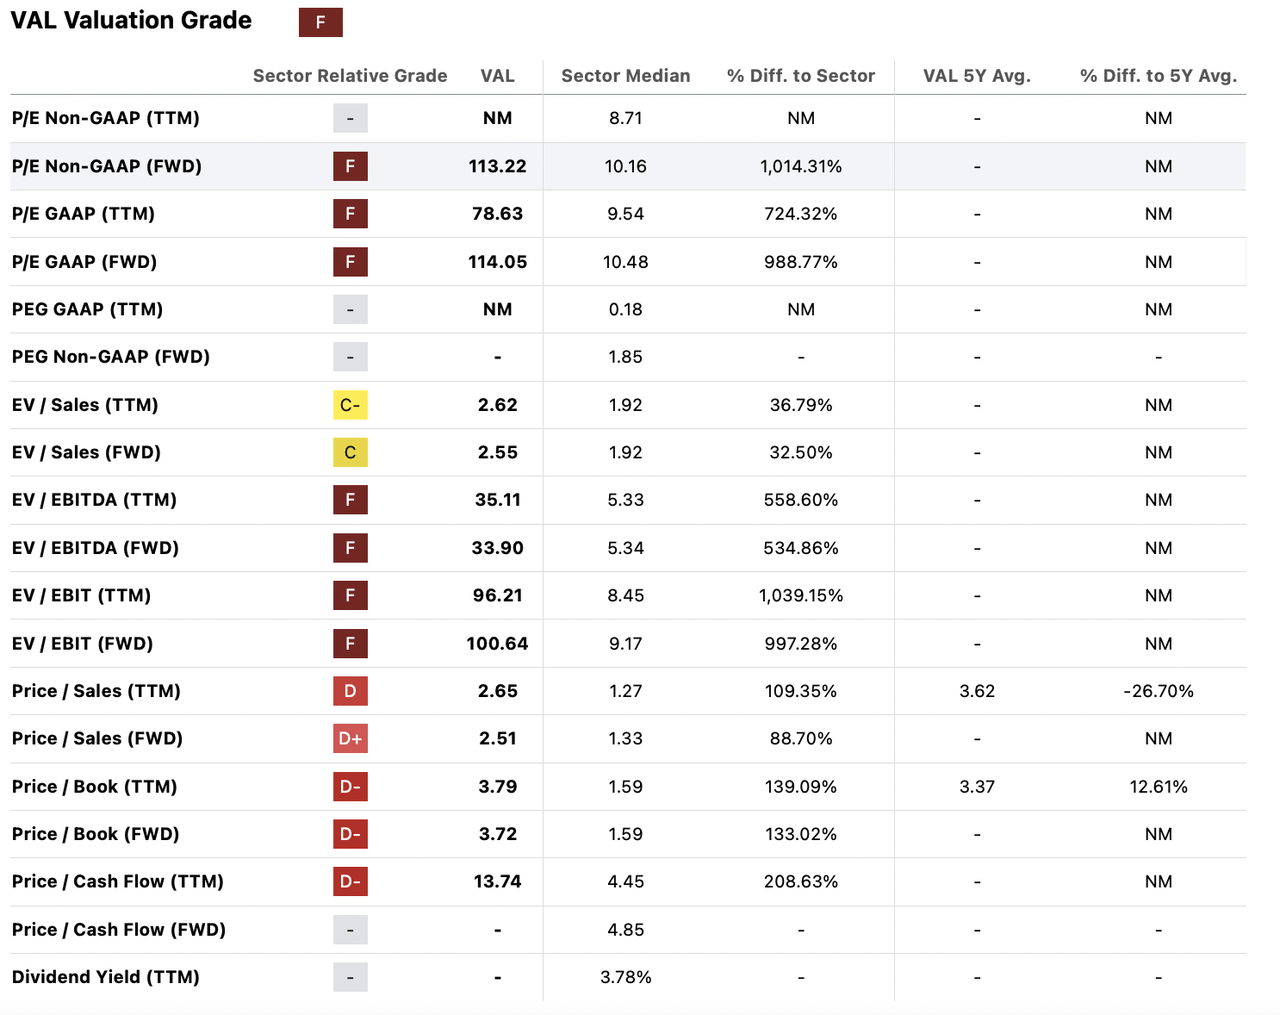
Let’s look a little at the valuation of the sector and where VAL compares to that. Basin the entire investments thesis on the earnings multiple right now, I think, is a mistake. The management anticipates significant EPS improvements by 2024 and beyond, which will be the reason for it possibly reaching $9.33 and putting VAL at an FWD p/e of 6.5. A 6.5 p/e would mean a discount of nearly 44%. The sales multiple is hard to compare as it heavily relies on strong production levels, but with that said, the coming years I do think it will be decreasing at a pretty good rate as VAL reactivates more vessels and boosts production capabilities. The p/s is at 2.51 FWD compared to 1.33 for the sector, leaving an 88.7% premium to pay compared to the rest of the energy sector.
The Value You Get
Outstanding Shares VAL (Seeking Alpha)
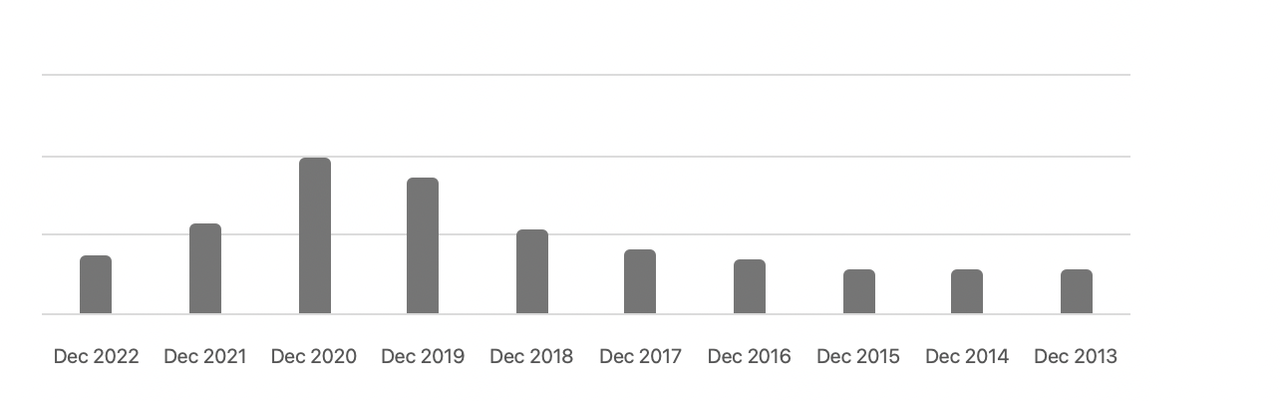
The two areas I look at when assessing the value that an investor would get are whether there is a dividend or an avid buyback program of shares. The chart for outstanding shares shows quite a lot of volatility these past few years, but the trend is going in the right direction at least, that being downwards. It topped out at 198 million but has decreased to 74.8 million now. In the past 12 months, VAL has bought back shares worth $152.6 million. With a market cap of $4.48 billion, this is a pretty significant amount and a bullish signal by the management. This was the first major buyback of shares in the past few years as well, which leads me to believe they see a lot of future earnings coming from reactivating vessels.
The Bear Thesis
The bear thesis for VAL but also a lot of other companies in the same sector is from volatility in commodity prices, like oil and gas. The stock price of VAL has been affected by how OPEC operates its production levels. The cut announced in 2023 was bullish for oil prices, but then significant oil production outputs in the US meant that prices stayed somewhat stable. For 2024 the cut of oil production is set to continue to the end of 2024 which should be bullish for oil prices. However, if there is an unexpected increase in production I do see the price of oil decreasing over the short term, which could be negative for the stock price of VAL and in turn investors as well.
State Of The Company
Balance Sheet Highlights (Seeking Alpha)
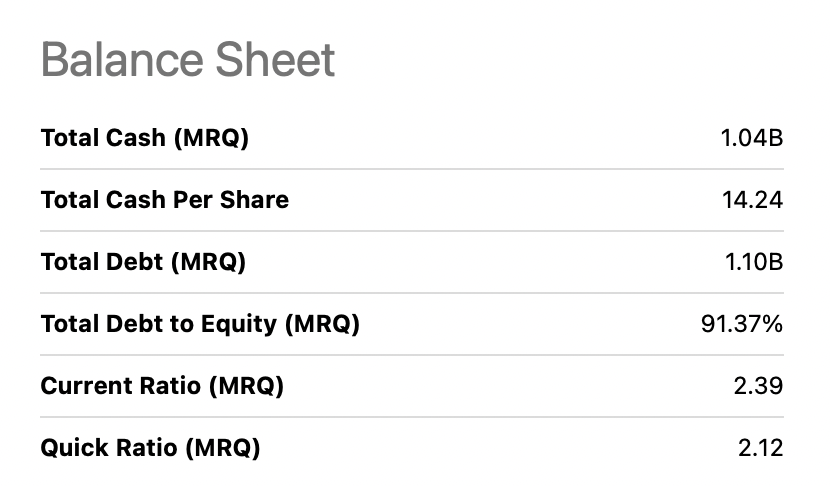
VAL has a cash position of $1.04 billion and with a market cap of $4.48 billion, it puts it in a very flexible position to handle any unexpected expense. In comparison to debts of $1.1 billion, we get a ratio of nearly 1 which is great. This means that VAL can cover all significant long-term liabilities and still be left in a good place. Nearly 50% of the total liabilities are with debt, and the remaining part is made up of $283 million in other non-current liabilities and $376 million in accounts payable. The balance sheet looks quite unleveraged for VAL. The equity debt might be high, but I would argue the large number of liquid assets that VAL holds ensures they can handle paying down debt when it matures.
Investment Conclusion
The offshore drilling market is quite significant and even with challenges for the industry like increased incentives for green energy, it’s a market with a long future still ahead. The management of VAL is what you are buying into here, and they are guiding for significant earnings recovery in 2024 and 2025 when they reactivate more vessels. The current earnings multiple doesn’t tell the full story, as we have learned, and I am assessing VAL as a buy.
Credit: Source link