
FABRICE COFFRINI/AFP via Getty Images
After a near 150% run-up through 2023, Palantir Technologies Inc.’s (NYSE:PLTR) market valuation had stalled since the new year started. Admittedly, Palantir’s long-term target for revenue expansion at 30% CAGR has largely been thrown out the door, given the change of operating dynamics today compared to when the ambitions were initially set. Investors have largely been wary of Palantir’s inherent exposure to some immediate operating headwinds. These include an increasingly lumpy government revenue recognition trajectory, in addition to volatile demand dynamics across its international operations, and the aftermath of a failed strategic commercial investment strategy.
Yet the company’s Q4 outperformance and stronger-than-expected forward guidance restored confidence in its prospects of capitalizing on emerging AI opportunities ahead that will be accretive to its existing business. The company’s Artificial Intelligence Platform, or AIP, remains a core multiple expansion driver for the stock, reinforced by favorable financial implications from the new solution’s deployment. Although management has yet to provide a clear understanding of how to optimize AIP monetization, the new solution has indirectly and singlehandedly transformed Palantir’s unit economics for the better.
From a growth perspective, AI complements Palantir’s existing “land and expand” business strategy. Through AIP bootcamps, Palantir has demonstrated a clear proposition in reducing customer acquisition costs for itself, while also enabling incremental productivity gains for customers. Specifically, the AIP bootcamps have effectively “compressed sales cycles” and reduced time-to-deployment from one to three months in traditional pilot programs, to now under five days. AIP has also reduced Palantir’s previously elevated exposure to post-sales support requirements, thus improving operating leverage favorable to its ongoing margin expansion efforts.
While PLTR stock trades at a premium to its software peers on a relative basis, we believe it remains fairly priced on intrinsic considerations at current levels. Specifically, current observations of efficiency gains realized within Palantir through AIP’s deployment is in itself sufficient for sustaining durability to the stock’s performance at current levels, in our opinion. Thus further detail on market share gains with AIP’s deployment, alongside greater clarity on its direct monetization strategy, would be value accretive factors to the stock from current levels. Relevant developments would also be critical for compensating continued lumpiness in the build-out of Palantir’s global government business.
Coming out of the latest earnings results, we remain confident in the accretive nature of impending AIP opportunities to Palantir’s outlook. Continued clarity on AIP’s direct monetization strategy across both commercial and government deployments would complement current observations of the solution’s indirect contributions to Palantir’s unit economics. A direct AIP monetization roadmap essentially holds the key to further multiple-expansion for the stock ahead from current levels.
Palantir Q4 2023 Earnings Overview
Both of Palantir’s top and bottom lines outperformed the upper range of management’s guidance, as well as market expectations, during Q4. Total revenue grew 20% y/y to $608.4 million, beating the upper range of management’s previous guidance and average consensus estimate by almost $6 million. Adjusted income from operations of $209.4 million also outperformed the upper range of management’s previous $188 million guidance by wide margins. The results highlight the favorable impact of ongoing disciplined spend management and improved operating leverage complemented by better unit economics realized through AIP deployments at scale (discussed in later sections).
U.S. commercial revenue growth of 70% y/y, underpinned primarily by momentum in AIP uptake, was a sole bright spot. Specifically, Palantir’s U.S. commercial business more than doubled its total contract value (“TCV”) y/y to $343 million, underpinned by new deals acquired across the $5+ million, $10+ million and $25+ million spending segments. The U.S. commercial business also acquired about 40 customers in Q4, up 22% sequentially compared to merely 12% in the preceding quarter.
Although the government business’ performance was comparatively muted during Q4, management expects reacceleration through 2024 as recently expanded programs with public agencies such as the Army start to ramp. The combined set-up across the commercial and government businesses kicks off a strong outlook for Palantir’s prospects in the year ahead. This is further complemented by TCV growth of almost 200% y/y to $1.2 billion, alongside net revenue retention (“NRR”) of 108% exiting 2023.
Admittedly, NRR has been relatively flat from 107% in Q2, which was down three points from the beginning of the year due to slower commercial uptake in Europe. But recall that NRR does not consider newly acquired sales in the LTM. This means the recent acceleration observed in the U.S. commercial business since AIP’s launch in April 2023 will not show up in NRR until Q2, and should not be overlooked.
The strong set-up exiting 2023 accordingly reinforces the stronger-than-expected guidance provided by management for the current quarter and the year ahead. Management expects revenue between $612 million and $616 million in Q1, which would represent 17% y/y and 1% q/q growth at the mid-point. For full year 2024, management expects revenue of $2.652 billion to $2.668 billion, which represents y/y growth of 20% at the mid-point. Strategic commercial contract revenue contributions are expected to fall further through the year to a 2% share of net sales (vs. 4% in 2023), highlighting strength in organic growth as AIP deployments continue to ramp.
Additive Direct AIP Contributions Not Yet Priced In
Although management has provided updates on how AIP has been contributing to Palantir’s top line revenue growth, there has yet to be an exact monetization roadmap for the product. Yet the indirect benefits stemming from AIP’s launch has been clearly accretive to Palantir’s business – both in the top line and in its unit economics. This leads us to believe that Palantir’s valuation at current levels is durably sustained by favorable indirect implications of AIP deployment on its fundamentals. And the stock is well positioned for prospects of further upside underpinned by the eventual disclosure of a proper monetization roadmap.
Data from Palantir SEC Filings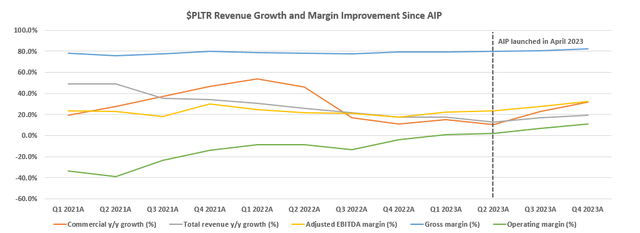
AIP Growth Impact
On the growth front, AIP has indirectly improved Palantir’s total addressable market, or TAM, by enabling incremental value propositions to customers. Specifically, AIP bootcamps hosted to date have discovered more than 200 new use cases for AIP, which is value-adding to existing Foundry deployments within the commercial setting. The company has also deployed 560+ AIP bootcamps to date, outperforming initial expectations for 500 before year-end by wide margins. This compares to 92 traditional pilots started two years ago for commercial-related deployments (e.g., Foundry). The reduced sales cycle for AIP has effectively improved time to value for customers. For instance, a recent AIP bootcamp resulted in the development of a “production-ready use case that provided $10 million of savings” for the participating customer.
Through the past eight months of AIP’s go-to-market, management has essentially gathered three key ways the new product has been additive to Palantir’s commercial revenue growth outlook.
- New customer acquisitions: This is evident in the consistent sequential acceleration in U.S. commercial customer count since AIP’s launch in April 2023. Specifically, Palantir now has 221 U.S. commercial customers, up 22% q/q. This compares to sequential growth of 12% observed in Q3 and 4% in Q2, highlighting the accretive value of AIP to Palantir’s commercial business. We believe the improved time to value for customers enabled by AIP has been a key driver of Palantir’s commercial market share gains observed in recent quarter. Specifically, Palantir’s swift ability in proving relevant AIP use cases and ensuing efficiency gains for customers within the two- to five-day bootcamp go-to-market strategy marks a key competitive advantage. Not only do AIP bootcamps shorten the sales cycle compared to complex and highly customer-specific traditional pilots, but they also incentivize a higher rate of conversions given immediately realizable value. This is evident in the increasing number of high-value multi-year deals over recent quarters, which also improves visibility to the company’s longer-term growth prospects and reinforces durability to the stock’s premium at current levels.
- Existing customer expansions: AIP is also complementary to Palantir’s land and expand business model, in our opinion, by improving ARPU across its growing customer base. AIP can essentially be viewed as a complementary system to Foundry, similar to a built-in generative AI assistant. Spanning AI-enabled assistants (i.e., AIP Assist), no-code builders (i.e., Pipeline Builder), and LLM-driven data analytics (i.e., AIP Logic), AIP essentially enables incremental customer-specific use cases “on top of [their] existing ontologies” in Foundry. This essentially drives adjacent consumption and, inadvertently, revenue to Palantir, thus complementing the land and expand business model critical to its growth roadmap. For instance, Palantir was able to demonstrate new use cases on top of one of its large telco customer’s existing ontology at AIP bootcamp within 24 hours. The result was a “multimillion-dollar expansion” of their existing sales contract coming out on the other side, underscoring the accretive value of AIP to Palantir’s existing business.
- Improved conversion of ongoing pilots: AIP’s accelerated time to value has also fast-tracked conversion of some ongoing traditional pilots. As previously mentioned, traditional pilots have historically lasted months to even years for some customers. This is not only critical to improving unit economics for Palantir (discussed in detail later), but also accelerates the pace of prospective revenue capture for the company. Specifically, initial pilots are often deployed for enterprise customers at low to no cost, with no guaranteed returns for Palantir. But the launch of AIP has already improved conversions, reinforcing the company’s capture of impending enterprise spending opportunities. This is evident in Palantir’s recent five-year $19 million contract signed with a large American CPG company, which came shortly after AIP’s launch despite a two-year pilot that preceded it.
Although management’s monetization strategy for AIP remains unclear, it is evident the new product has been indirectly accretive to Palantir’s growth. AIP also plays a critical role in enabling recent acceleration observed in Palantir’s U.S. commercial business. Looking ahead, we also view AIP as a critical compensatory factor for Palantir’s inherent exposure to several company-specific growth challenges. These include persistent volatility in government revenue recognition, and the lingering aftermath of its failed strategic commercial contract strategy adopted a few years back prior to the industry downturn.
AIP Cost Impact
More importantly, the indirect value of AIP is visibly evident in Palantir’s substantial unit economic improvements. As discussed in the earlier section, AIP is a complementary solution to the Foundry platform. In addition to incremental value-add use cases for customers, AIP has also played a critical role in improving operating leverage at Palantir:
- Compressed sales cycle and reduced CAC: Recall that Palantir’s traditional pilot deployments for Foundry have typically been offered at no to low costs to customers, with no guaranteed conversion. The pilots can typically last from months to days, highlighting a lengthy and complex sales cycle, which inadvertently results in elevated customer acquisition costs (“CAC”) for Palantir. The AIP bootcamps, in contrast, typically last no longer than five days. AIP bootcamps essentially improve conversion for Palantir as earlier discussed, while also significantly compressing the sales cycle from months to days by incentivizing adoption of its offered platform solutions. They also reduce customer acquisition costs (“CAC”) for Palantir by allowing sales to multiple clients at once.
- Reduce post-sales servicing costs: Admittedly, Foundry is a complex product. Customers have often highlighted inefficiencies related to the lack of user expertise and complex system configuration during the early days of implementation. This has likely been a key driver of Palantir’s sales personnel costs in the past, due to the increased requirement for post-sales support at initial deployment. Yet AIP addresses this inefficiency for Palantir. Specifically, the AIP bootcamps typically equip prospective customers with use cases based on their respective enterprise needs. This allows AIP deployments to generate value for customers at day one of implementation, while reducing post-sales support costs for Palantir. AIP itself also improves the usability of Foundry. As discussed earlier, one of the key functions of AIP is its role as a built-in generative AI solution within the Foundry operating system. Through key functions such as AIP Assist, which is a built-in Foundry chatbot that helps users navigate the solution and execute company-specific data tasks, the complementary product essentially reduces the burden of post-sales support needs on Palantir. Taken together, AIP significantly improves Palantir’s growth trajectory and cost structure by improving scalability of sales.
The combination of compressed sales cycle, reduced CAC and decreased post-sales servicing costs enabled by AIP also complements Palantir’s ongoing cost-cutting efforts. Specifically, the AIP-related efficiency gains support Palantir’s ongoing stock-based compensation reduction efforts by reducing its sales and marketing, and general and administrative personnel cost exposure. Improved scalability within the business also complements the annualized cost reductions realized by Palantir over the past the past year of implementing “disciplined spend management.” This effectively enables sustained margin expansion with growth at scale for Palantir, which improves its cash flow prospects and, inadvertently, valuation outlook.
Fundamental Considerations
The continued ramp of AIP deployments, particularly in the commercial business, would reinforce Palantir’s market share gains in enterprise AI and data solutions. This would be key to offsetting the company’s inherent exposure to fluctuations in the government revenue recognition trajectory, given improved visibility of the commercial business’ contracted / SaaS revenue model. We believe AIP results delivered to date, despite having no certain monetization trajectory, reinforces confidence in Palantir’s outlook. This is evident in commercial revenue reacceleration in recent quarters, which is more prominent in U.S. operations, nearing Palantir’s previous target for a 30% CAGR over the longer-term.
Adjusting our previous forecast for Palantir’s actual Q4 performance, management’s forward guidance, as well as our foregoing discussion on AIP implications, we expect 19% y/y growth to total revenue of $2.66 billion in the current year. Specifically, much of the growth will come from the commercial business given expectations for continued momentum in AIP deployments. Commercial revenue growth is expected to accelerate by five points y/y to 25%, resulting in segment sales of $1.25 billion. Meanwhile, reacceleration expected in the government business is expected to be comparatively muted.
Our forecast estimates a one-point y/y growth acceleration to 15% to full year 2024 government revenue of $1.41 billion. This is consistent with management’s acknowledgement of a slower ramp in government software deployments, and the delayed timing of larger contract awards granted in late 2023. The set-up implies more evident reacceleration in the government business in the back half of 2024, with further momentum heading into mid-decade.
Author
On the cost front, we expect the continued ramp of AIP deployments to result in a three-point expansion to operating margins in 2024. As discussed in the foregoing analysis, the internal efficiency gains enabled by AIP’s go-to-market strategy has likely played a critical role in reducing Palantir’s operating cost exposure stemming from personnel compensation in 2H23.
Data from Palantir SEC filings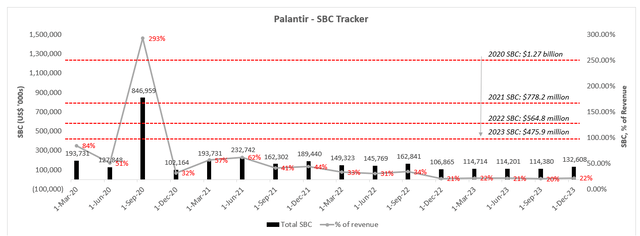
And the continued growth of AIP uptake at scale is expected to further said improvements to Palantir’s operating leverage. This would also complement the annualized cost-savings realized by the company’s disciplined spend management implemented through the previous year, and enable further margin expansion at scale.
Author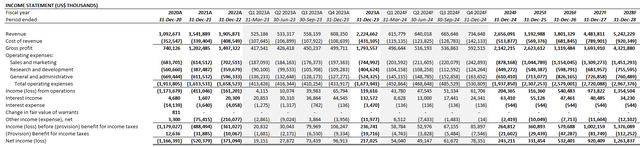
Palantir_-_Forecasted_Financial_Information.pdf
Valuation Considerations
We are increasing our base case price target for Palantir to $20, which is consistent with the stock’s post-earnings price. The base case price target is in line with our expectations that Palantir’s current valuation premium to peers on a relative basis is intrinsically supported by the favorable indirect fundamental implications from AIP deployment. And the stock remains well-positioned to benefit for incremental upside potential from current levels should management provide greater clarity on AIP’s direct monetization roadmap. Stronger than expected reacceleration in the government business through the remainder of the year would also be value accretive to the stock.
Author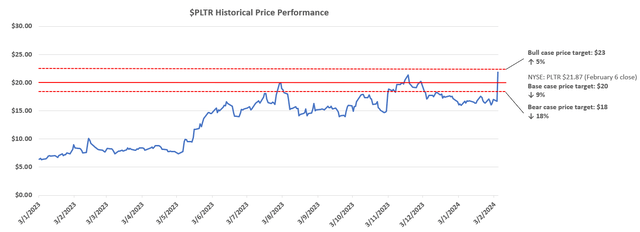
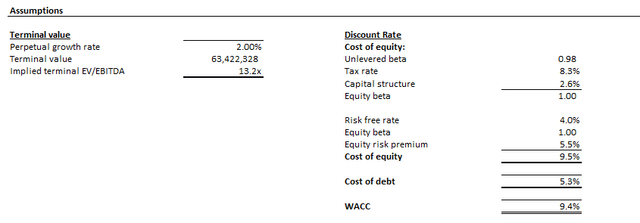
Our base case price target is derived under the discounted cash flow, or DCF, approach. The valuation analysis takes into consideration the cash flow projections in conjunction with the base case fundamental analysis discussed in the earlier section. A WACC of 9.4% is applied, which is consistent with Palantir’s capital structure and risk profile. The analysis also assumes an implied perpetual growth rate of 2%, which is applied on projected terminal cash flows and is in line with the pace of steady-state economic growth across Palantir’s core operating regions.
Author Author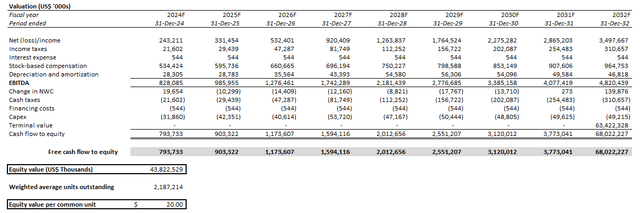
Final Thoughts
We remain confident in Palantir Technologies Inc. stock’s durability at current levels, given support from the underlying business’ consistent delivery of positive progress on AIP monetization. The new product has largely been additive to Palantir’s existing business, especially in the commercial segment. This essentially positions the stock for further upside potential should management provide further clarity on the intended direct monetization roadmap for AIP ahead of an expanded TAM enabled by the advent of generative AI and its mass market adoption.
Meanwhile, the biggest overhang on the stock remains Palantir’s muted government business due to its inherent exposure toa lumpy revenue recognition trajectory. The company also faces the adverse aftermath of its strategic commercial contract strategy. Yet favorable AIP impact observed to date across both of Palantir’s top and bottom lines remains compensatory to the immediate company-specific challenges. We believe the stock’s prospects remain skewed to the upside from current levels, as Palantir continues to ramp the deployment of its AIP solution and capture adjacent opportunities that are additive to its existing business.
Credit: Source link