
baona/iStock via Getty Images
By Sam Peters, CFA
Building an Adaptive Framework
There is no formula to eliminate uncertainty when it comes to the future. We believe the best approach is to accept it and embrace probabilistic thinking. This is exactly what our investment process is designed to do — give us a competitive advantage by constantly learning and adapting rapidly as we observe markets.
This adaptation process is a cornerstone of how we are formulating our thoughts for 2024. The first step is developing a probability framework around potentially key 2024 scenarios, allowing us to update our own probabilities as we observe critical events and to falsify erroneous forecasts as the year progresses. A crucial second step is to try and unpack what markets have priced in, as it allows us to compare our own probabilities against the market’s and identify what surprises could move markets.
The Value Equity team assigned probabilities to three broad scenarios: a recession, a soft landing and a no landing where inflation stays sticky above 2% and starts to re-accelerate.
Scenario #1: Recession
We estimated that the probability of a recession in 2024 was roughly 30%, with a range of 15% to 60%, while we estimated that the market was pricing in a recession probability of roughly 20%. One of the most difficult questions we asked ourselves in pondering this scenario was were models so wrong in confidently calling for a recession in 2023? We think markets are too focused on monetary policy and have not incorporated the massive change that is underway from fiscal policy expansion, including infrastructure buildouts and energy transition. In addition, we were wrong in underestimating the continued resilience of U.S. shale oil and gas supply and the Strategic Petroleum Reserve release. There has never been a recession since 1970 without both higher interest rates and an oil spike. With oil down 3% since the Ukraine invasion, a critical recession variable is missing.
Exhibit 1: Oil Prices Show Little Sign of Recession on Horizon
* Price movement in WTI Crude is calculated as the percentage change in price from one year prior to the last rate hike to the first job losses since 1970. As of Dec. 11, 2023. Source: St. Louis Federal Reserve, Raymond James Research.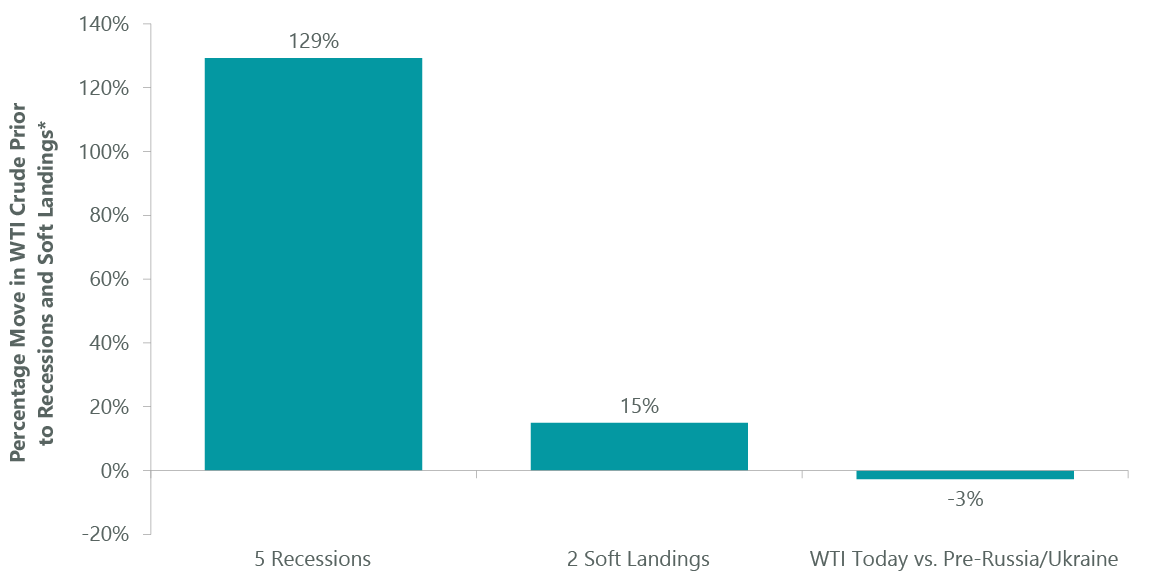
* Price movement in WTI Crude is calculated as the percentage change in price from one year prior to the last rate hike to the first job losses since 1970. As of Dec. 11, 2023. Source: St. Louis Federal Reserve, Raymond James Research.
On the adaptation front, our ability as value managers to buy cheaper recession insurance in the fourth quarter and the fundamental strengths of our portfolio holdings, with resilient free cash flows and fortress balance sheets, suggests our portfolio turnover in a recession may not be significant. This is particularly true if a recession requires an oil spike, given our bullish views on energy. Rather, the turnover would come when investors get scared and valuation spreads spike materially. We are always active during windows of extreme investor fear when the valuation math gets very easy, but the emotions are hard – there are great opportunities to layer in high forward returns from a behavioral overreaction.
Scenario #2: Soft Landing
Just as markets were confident of a recession in 2023, markets are now very confident of a soft landing. Our team estimated a 50% probability of a soft landing, but think the market is pricing in a 70% probability amid tight credit and valuations spreads, and very low measures of equity volatility. Ironically, fixed income volatility has been well above equity volatility measures since early 2021. It’s a bit of a paradox that traditionally calmer fixed income markets can be so much less certain than equity markets, suggesting the equity market is overconfident in its ability to read an uncertain future.
Exhibit 2: Bond Volatility Surpasses Equity Volatility
As of Dec. 31, 2023. Source: Bloomberg.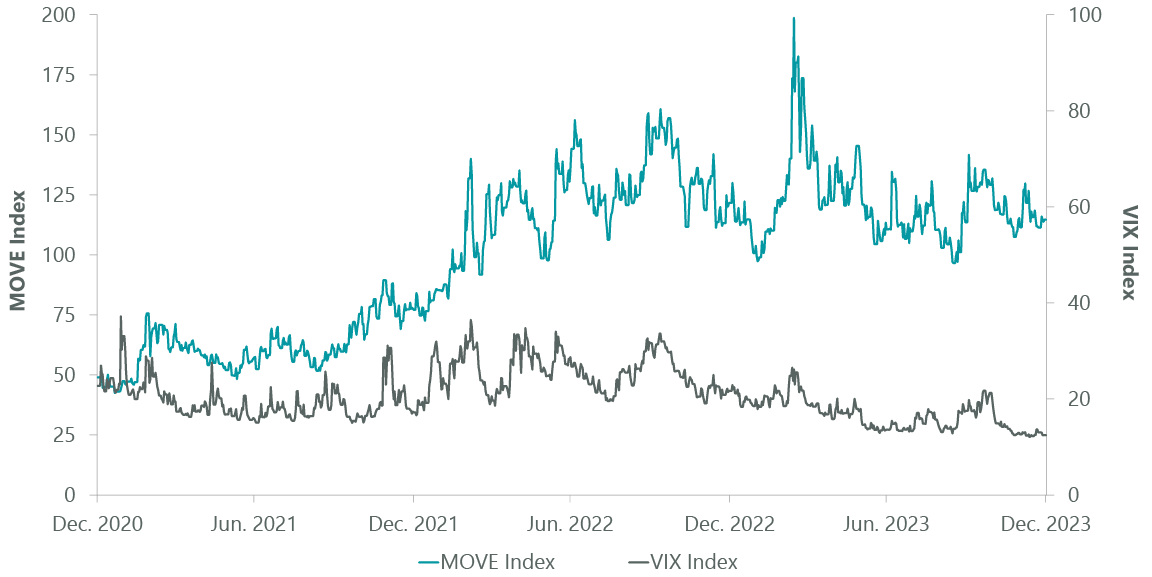
As of Dec. 31, 2023. Source: Bloomberg.
Adaptation in a soft landing scenario would also likely not require material portfolio turnover. Rather, we would expect the market to continue to broaden out, as it did in late 2023. With indexes at extreme concentration levels, a continued broadening out would channel more capital to areas with strong fundamentals and attractive valuations, places where our active valuation investment process has led us. It would not take much, given how one-sided investor positioning is in mega cap U.S. growth stocks.
Scenario #3: No Landing
We think a no landing scenario is the event that would trigger major volatility. Our estimate of no landing was roughly 20%, which is at least double what the market has priced. Our bias is that inflation will be cyclical over the next several years given massive fiscal expansion and ongoing deficits, accelerating capital investment required for the energy transition and infrastructure buildout, and the shift in geopolitics that dampens structural deflation. As such, we would expect inflation to bounce above 2% and cycle higher if we avoid a recession. Ironically, the massive decline in interest rates as markets priced in a soft landing late in the fourth quarter may be the key trigger for higher inflation later in 2024. We are coming off one of the most aggressive loosening of financial conditions ever, and markets are a huge causal factor in driving economic activity via reflexive feedback.
Adaptation in a no landing scenario would require higher portfolio turnover, but much less than for investors not accounting for this possibility. In a recent survey by Bank of America, global fund managers were the most underweight commodities versus bonds since March 2009. This level of complacency in anchoring on one scenario gives us the ability to buy no landing insurance on the cheap. Again, we are not betting on scenarios, but rather inverting the process and seeing where embedded expectations in possible futures are selling well below business value at the stock level. Where we can buy energy and materials stocks at high-single-digit to low-double-digit free cash flow yields, with almost no debt, and attractive dividend and buyback yields, we will take it — especially when we get such a valuable inflation option.
Regardless of what scenario plays out, our focus remains on finding stocks selling below business value and where we have a more optimistic view of future fundamentals than what the market has priced. This active valuation discipline requires that we get the fundamentals right with very little help from valuation multiple expansion.
Sam Peters, CFA is a Portfolio Manager and co-manages the Value Equity Strategy and the All Cap Value Strategy, and has over 30 years of investment experience. Sam earned a BA in economics from the College of William & Mary and an MBA from the University of Chicago. He received the CFA designation in 1997.
Credit: Source link