
mohd izzuan
HealthEquity (NASDAQ:HQY) in our opinion is a great trading vehicle. We have previously viewed this ticker as a buy in the $50s, a hold in the $60s, and a sell in the $70s and $80s. Right now, the range has tightened even more, and seems to be a buy in the low $60s and sell in the low $70s. It has been a pretty defined range.
While it is good news that HealthEquity stock has not dropped far below the bottom end of the range, long-term investors have been met with frustration as the stock seemingly just cannot break out. So how does one make money here? By simply trading it. Sometimes it seems that trading is frowned upon by investors. But we are not talking about day trading (which is basically gambling largely). We are talking about trading over a period of weeks and months using defined ranges. Frankly, our trading destroys buy and hold approaches, but the point of this column here is that the just-announced performance is likely to keep this stock pinned in this range we have identified.

So overall, given where the stock is in the range, we have a hold rating here. The simple fact is that this has not made for a great investment but has been a strong trading name. Buy and hold investors have seen very little in the way of gains in the last 5-6 years. But if you bought and sold anywhere close to the above ranges a few times, you would be far outpacing investors and the market by trading. That is what we do.
There are reasons to like the company. The company has a large total addressable market. The company works in the healthcare savings field. The company helps to provide HSAs, HRAs, and FSAs which can bolster a traditional health insurance plan by providing savings for non-covered medical expenses. Most of these consumer HSAs and HRAs are offered by traditional health insurance providers. Most of the monetization of these plans comes from the custodial assets. HealthEquity has been working at expanding its offerings and drawing in new assets over the last few years. In this column, we check back in and discuss the just-reported Q3 earnings.
HealthEquity saw strong Q3 results. Revenue beat versus consensus estimates, and the bottom line earnings once again surpassed estimates. Still, while there is some growth here, you are paying up for it, as the valuation is less than attractive here. Take a look at Seeking Alpha’s Quant valuations:
Seeking Alpha HQY Valuation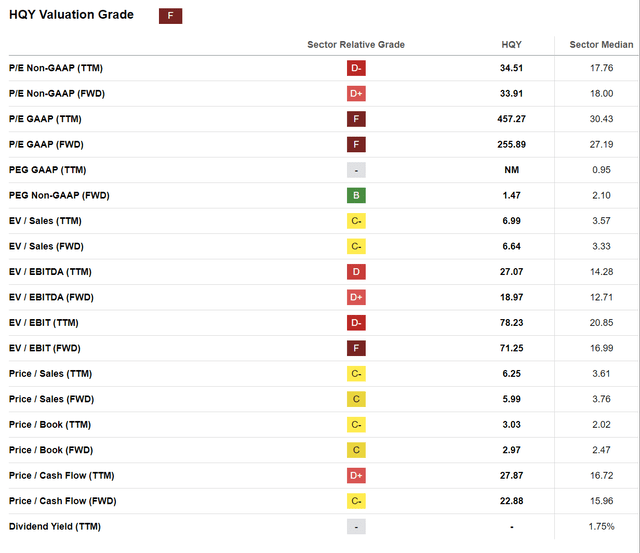
So, the stock is expensive and receives a grade of “F” on valuation. The PEG ratio is one of the only attractive components to the valuation. The price to cash flow at 22X FWD is high. The EV/EBIT numbers are very rich over 70X, while 34X FWD EPS is a lot to pay. Now, a company can grow into the valuation, if the growth is there. But the growth here, while certainly positive, is not at a blistering pace that supports such valuation. As such, we think HealthEquity, Inc. stock remains rangebound here. Thus we rate it a ‘hold’ overall, but stand by our ranges previously identified.
The top line did grow, hitting $249.2 million. This was an increase of 15.3% compared to $216.1 million last year. This was also a beat by $5 million over estimates. The company reported service revenue of $107.5 million, custodial revenue of $106.6 million, and interchange revenue of $35.1 million. Adjusted EBITDA was $95.6 million, an increase of 30% from last year. Net income expanded to $14.7 million, or $0.17 per share, while adjusted net income was $52.2 million, or $0.60 per share, up from $32.4 million, or $0.38 per share. If the company can continue to grow EPS like this, then we could possibly see the stock finally bust out of the upper end of the trading range, but management will need to execute. And in the ever-changing landscape of healthcare in America, that is a challenge.
The good news is that much of these results were driven by more accounts under management. Total HSAs were 8.3 million, an increase of 8% year-over-year, including 592,000 HSAs with investments, an increase of 12% year-over-year. Total accounts reached 15.3 million, including 7.0 million other consumer-directed. Total HSA assets rose 12% to $22.6 billion from last year. The company also recently acquired “BenefitWallet” and their HSA portfolio from Conduent Business Services in September. That acquisition adds $2.8 billion of HSA Assets held in approximately 665,000 customer accounts. HealthEquity ponied up $425 million, and while still ongoing, may pay up to $20 million in transfer-related expenses. The acquisition is expected to close in multiple tranches during the first half of fiscal 2025. As we look ahead, there is guidance for growth.
For this fiscal year, management sees revenue of $985 million to $995 million and net income between $34 million and $39 million, with adjusted EPS of $2.08 to $2.16 and adjusted EBITDA of $350 million to $360 million. For an early look to fiscal 2025, management is projecting revenues will be up about 16% or so to $1.15 billion with Adjusted EBITDA of approximately $435-$445 million. Thus, the growth is there, though HealthEquity, Inc. stock is already valued for it. We suspect it will be difficult for shares to get much past $80, and so that is where we remain sellers of the stock.
Take home
HealthEquity, Inc. stock is a hold here for the long-term investor, But we have defined trading ranges. We as traders are buyers of HealthEquity, Inc. stock in the $55 range-$60 range generally, but the range has narrowed to buying in the $60s and selling in the $70s as late. Don’t be afraid to trade HealthEquity, Inc., this stock is a wonderful vehicle for those types of gains.
Credit: Source link